Insurance claim documentation for Miami water and mold losses
You have water damage or mold, an insurance claim to file, and an adjuster asking for proof of what happened, while you are still trying to get the house dry.
Good records make a claim easier to follow. We document the damage and the work as it happens, organize it so an adjuster can read it, and talk with the adjuster about what we found. You stay in charge of the claim itself.
At a glance
- Service
- Insurance Claim Documentation
- Group
- After the Cleanup
- Hours
- Phones answered 24/7
- Office
- 1428 Brickell Avenue, Floor 3, Miami
- Covers
- Miami-Dade and Broward
When you call, we start documenting on the first visit: photos before anything is moved, moisture readings, a scope of work and an equipment log. We keep adding to the file daily until the job is done, then give you the full set. Florida's notice deadline for a new residential claim is 1 year from the date of loss, so start the paperwork early.
What we document
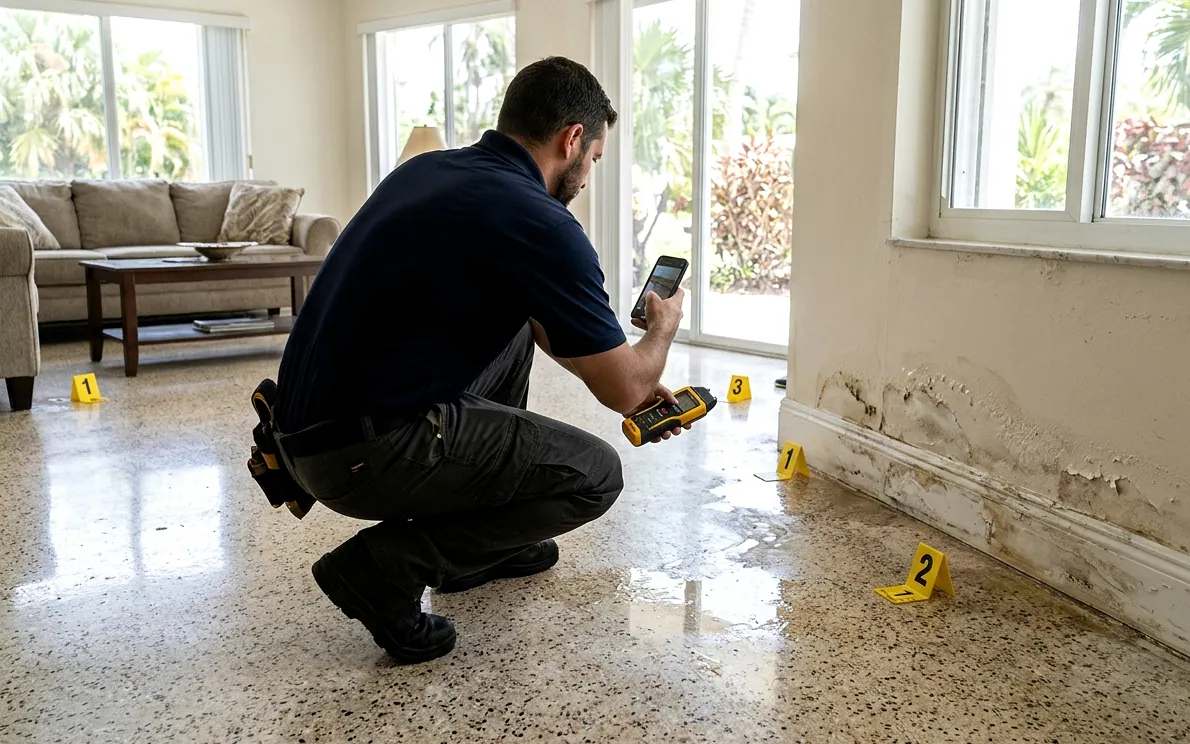
The file starts before the crew moves anything. We photograph each affected room, the source of the water if it is visible and the materials that are wet. Readings are taken with moisture meters and noted by location.
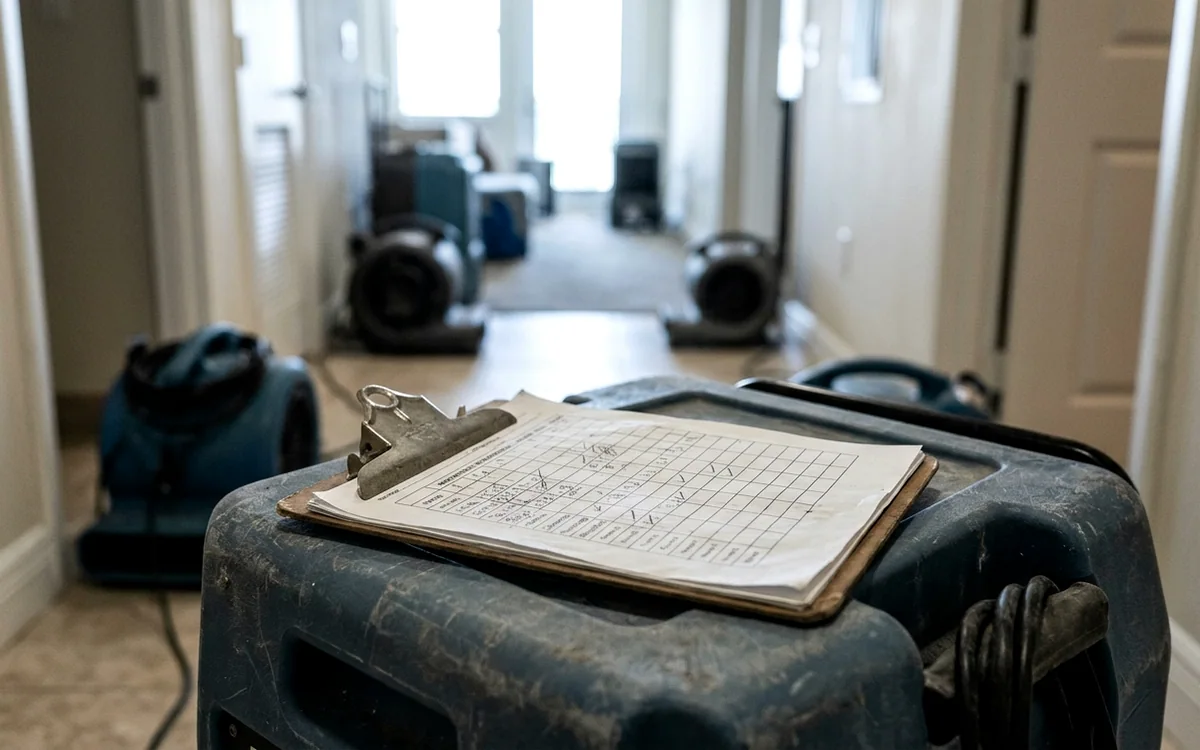
As work goes on, the file grows. Every material removed, every piece of equipment placed and every day of readings is added, so the record shows the job from start to finish.
- Dated photos before, during and after
- Moisture readings by room and material
- Moisture maps showing how far water spread
- Written scope of work and materials removed
- Equipment log with units and days run
- Water category and class noted at the start
Talking with your adjuster
Adjusters often want to see the damage, the readings and the reasons behind each step. We can meet them on site, walk them through the work and answer questions about drying and removal. We explain what we did and why.
We do not negotiate your settlement, interpret your policy or argue coverage. Those are your decisions, and you can bring in your own advisor if you want one.
What we do not do
We are a restoration company, not a public adjuster, and we do not act as one. We do not give legal advice about your claim or your policy. If you want help with coverage disputes, a public adjuster or attorney is the right person to ask.
We also do not take an assignment of benefits. Florida law makes any assignment of post-loss benefits under a residential or commercial property policy issued on or after January 1, 2023 void and unenforceable. You stay the one who deals with your insurer.
Florida deadlines to know
Under Section 627.70132, a new or reopened Florida residential property claim is barred unless notice is given to the insurer within 1 year of the date of loss. A supplemental claim must be noticed within 18 months. For hurricanes and other weather events, the date of loss is the landfall date or the date NOAA verifies the event.
These deadlines came from SB 2-A, signed December 16, 2022. Your policy and your insurer set the rest of the process, so check with them about your own timeline.
Flood and condo claims
FEMA states that most standard homeowners policies do not cover flood damage, which is bought separately. NFIP residential policies cover up to $250,000 for the building and up to $100,000 for contents. If rising water came in from outside, your records may go to a flood insurer as well as your homeowners carrier.
In a condo, the association insures and repairs the condominium property as originally installed, while the unit owner insures items such as floor, wall and ceiling coverings, fixtures, appliances and cabinets. Clear records help each insurer see its part of the loss.
Unincorporated Miami-Dade County had 116,895 NFIP flood policies in force as of December 2024, the most of any Florida community. In zones AE, AH, AO and VE, flood insurance is mandatory for federally backed mortgages, so many Miami-area losses involve a flood policy alongside a homeowners policy.
When to call about insurance claim documentation
Adjuster asked for photos
If the insurer wants proof of the damage, photos taken before cleanup are the most useful.
Unit-to-unit condo leak
When water crossed from one unit to another, several policies may be involved and records help keep them straight.
Hidden water in walls
Damage that is not visible needs readings and moisture maps to show how far it went.
Storm or flood water
Weather losses may involve both a homeowners and a flood policy, each with its own paperwork.
Mold after a leak
Mold tied to a water event needs a clear record of the source and when it was found.
Long drying job
Drying that runs many days needs daily readings and an equipment log to explain the time.
What happens after you call
Photograph before work
We take dated photos of every affected area before anything is moved or removed.
Measure and map
Moisture readings and maps show where water traveled and which materials are wet.
Write the scope
We list what needs drying, what must come out and why, by room.
Log daily progress
Readings, equipment and work done are added to the file every day.
Meet the adjuster
If asked, we walk the adjuster through the site and the records.
Hand over the file
When drying is done, you get the full set of photos, logs and scope notes.
What insurance claim documentation usually costs in Miami
Documentation is part of the drying and mold work, not a separate service. These are typical Miami-area ranges for the work the records describe.
| What is priced | Typical range |
|---|---|
| Water damage restoration, typical job | $1,395 to $6,240 |
| Water extraction, per sq ft, clean to black water | $3.85 to $7.35 |
| Restoration labor, per hour | $71 to $197 |
| LGR dehumidifier, per day | $86 to $124 |
What your insurer pays depends on your policy, deductible and their review. Our price depends on the size of the loss and the drying time, and is set after an on-site look. See every cost range we publish.
Insurance Claim Documentation: common questions
Do you sign an assignment of benefits so you can bill my insurer directly?
No. Florida law makes post-loss assignments of benefits void on residential and commercial property policies issued on or after January 1, 2023, and we do not take them. You keep control of your claim.
Are you a public adjuster?
No. We document the damage and the work, and we talk with your adjuster about what we found. If you want someone to negotiate the claim for you, a public adjuster is a separate hire.
How long do I have to report a water damage claim in Florida?
Under Section 627.70132, notice of a new or reopened residential property claim must be given within 1 year of the date of loss, and a supplemental claim within 18 months. Check your policy for its own reporting requirements.
Should I wait for the adjuster before you start drying?
Usually no. The EPA advises drying within 24 to 48 hours to prevent mold, and many policies ask you to limit further damage. We photograph and measure everything first so the adjuster can still see what was there.
Can I get copies of the moisture logs and photos?
Yes. You receive the full file when drying is done, and we can share it with your adjuster or association if you ask.
Often needed on the same job
Water Damage Restoration
Extraction, drying and repair after any water event in a home or unit.
See the serviceCondo Water Damage
Unit-to-unit leaks in high-rises, worked alongside building management.
See the serviceLeak Detection & Moisture Mapping
Thermal imaging and meters to trace hidden water inside walls and floors.
See the serviceStorm & Hurricane Water Damage
Wind-driven rain, surge and roof breaches after tropical weather.
See the serviceWater where it should not be? Call now.
A person answers every call, day or night. Tell us what got wet and when it started, and we will tell you what happens next.